What Owning a Home Really Costs Each Year
The mortgage is the number everyone knows. Taxes, insurance, utilities and upkeep can add more than $20,000 a year on top of it. Here's how to estimate yours and build a repair fund that holds up.
Rooftop Daily editors choose every topic independently. Some guides include labeled partner offers, and we may be paid when you request a quote. How we make money
In this guide
Ask a new homeowner what the house costs and you’ll hear the mortgage payment. Ask them again after the first year and you’ll hear about the water heater, the tax bill that went up, the insurance renewal and the garage door spring that snapped on a Sunday. Those costs are as real as the mortgage. They just don’t arrive on a schedule.
The short answer
Beyond the mortgage, Bankrate’s 2025 study estimated the average single-family homeowner spends about $21,400 a year on maintenance, utilities, property taxes, insurance and internet. Your number depends on your home’s age, size, location and condition. The most reliable way to budget for repairs is by system: estimate when your roof, furnace, water heater and other big items will need replacing, divide each cost by the years left, and save that every month, plus a smaller amount for routine upkeep.
Here’s how the first year often goes. The mortgage payment is exactly what you planned for. Then the water heater fails in March, the property tax bill rises after a reassessment, and the insurance renewal comes in higher. None of those is a disaster on its own. Together, they’re the reason a separate house budget matters.
The costs on top of the mortgage
In a 2025 study, Bankrate estimated these average yearly costs for a single-family home, as reported by the Mortgage Bankers Association:
The numbers
| Cost | Average per year (2025) |
|---|---|
| Maintenance | $8,808 |
| Utilities and energy | $4,494 |
| Property taxes | $4,316 |
| Homeowners insurance | $2,267 |
| Internet and cable | $1,515 |
| Total | about $21,400 |
Source: Bankrate, 2025 hidden costs of homeownership study, as reported by MBA NewsLink, June 2025. National averages across 49 states; your costs will differ.
Insurance is the line moving fastest for many people. Insurify, a comparison site, projects the average homeowners premium will reach about $3,057 by the end of 2026, after a 12% rise in 2025. If yours jumped, see why your home insurance went up.
Why the maintenance number is so slippery
Here’s the honest problem with any single “average maintenance” figure: it depends entirely on how it’s measured. Bankrate’s estimate is $8,808 a year. The Census Bureau’s 2021 American Housing Survey, which asks owners what they actually spent, found much lower medians: owners of homes built before 1950 spent a median of $1,800 a year on upkeep, including improvements, and median routine maintenance was about $540.
Both can be true. Most years, most houses need little. Then the roof goes, and that year costs $10,000 or more. Averages smooth that out; your bank account doesn’t. The Census data also shows when the spending clusters: new owners of older homes spent a median of $3,900 a year, versus about $1,500 for owners who had been there 10 years or more.
That’s also why the old rule of thumb, set aside 1% of your home’s value each year, is only a starting point. It doesn’t know whether your furnace is 3 years old or 23.
Advertisement
A better way: budget by system
Instead of a percentage, build a sinking fund around the things that will actually wear out.
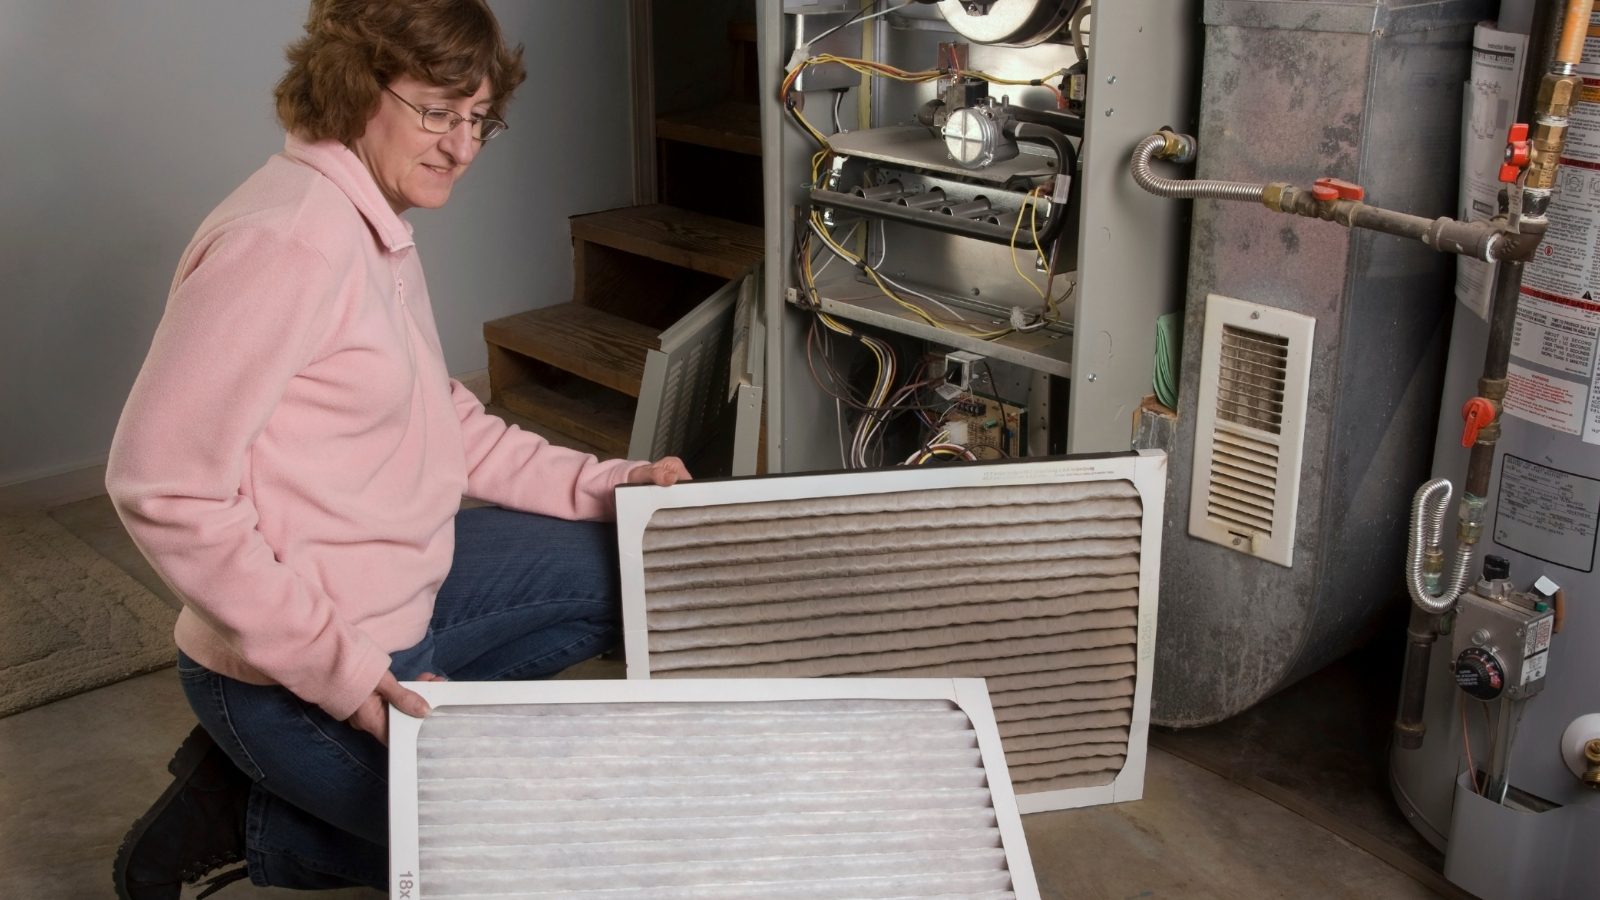
- List the big systems and their ages: roof, furnace or boiler, air conditioner or heat pump, water heater, major appliances. Our guide to how long things last has typical lifespans and how to find each one’s age.
- Estimate the replacement cost of each. For example, This Old House puts a typical furnace at about $4,800 and an asphalt roof on a 2,000-square-foot house at about $10,300 in 2026. Your own quotes are better.
- Divide by the years left. Use InterNACHI’s typical lifespans as a guide.
- Add a routine-upkeep amount for gutters, filters, small repairs and service calls.
- Save the total monthly, in a separate account, and leave it alone.
The numbers
| System | Age | Typical life | Years left | Replacement estimate | Save per month |
|---|---|---|---|---|---|
| Asphalt roof (architectural) | 22 | about 30 | 8 | $10,300 | about $107 |
| Gas furnace | 16 | 15–25 (plan on 20) | 4 | $4,800 | $100 |
| Routine upkeep | — | — | — | — | your estimate |
Example only. Lifespans: InterNACHI. Costs: This Old House 2026 national averages. Use your own home’s ages and local quotes.
The point of the exercise isn’t precision. It’s that the monthly number is visible before the bill is. In this example, the roof and furnace alone call for about $200 a month, which is very different from what most people assume.
When the fund isn’t there yet
If you’ve just bought an older house, you may not have years to build the fund before something fails. You have a few options: a home warranty to cover systems and appliances for a fixed monthly fee (see is a home warranty worth it?), making the most-at-risk repair first while you save for the rest, or financing a single big repair while you build the fund behind it. Our guide to paying for a big home repair compares the options.
Call a pro
Don’t count your home equity as your repair fund. Borrowing against the house for every repair adds debt secured by your home, and the cost of that borrowing adds up. Use it for the big, rare jobs, and keep cash for the rest.
Keep the other costs from creeping
- Shop the insurance with the same coverage every year or two.
- Check your property tax assessment when it arrives; most places have an appeal process if it looks high.
- Cut the energy bill with the cheap fixes in our fall-to-winter checklist: thermostat setbacks, air sealing and filter changes.
Your next step
Open a separate savings account tonight and name it “house.” Then spend 20 minutes listing your big systems and their ages, run the math above, and set up an automatic transfer for the monthly number. Even half of it is better than finding out the hard way.
Advertisement
Questions readers ask
How much should I budget for home maintenance each year?
Estimates vary widely. Bankrate's 2025 study put average annual maintenance at $8,808, while the Census Bureau's 2021 American Housing Survey found far lower median spending. A better approach is to budget by the age and replacement cost of your home's big systems, plus a smaller amount for routine upkeep.
Is the 1% rule for home maintenance accurate?
It's a rough starting point, not a plan. It ignores your home's age, size, climate and condition. An older home with an aging roof and furnace can need much more in a given year; a newer one may need much less.
What are the hidden costs of owning a home?
Beyond the mortgage, the big ones are maintenance and repairs, property taxes, homeowners insurance and utilities. Bankrate's 2025 study estimated those costs at about $21,400 a year on average for a single-family home.